Ally Credit encompasses the full suite of borrowing solutions and credit-tracking tools offered by Ally Financial Inc. This includes consumer credit cards, auto loan financing, point-of-sale loans via Ally Lending, and home mortgages, alongside integrated online credit score monitoring for existing account holders through Ally Bank's digital portal.
The Scope of Ally Credit Offerings
Ally Financial Inc., formerly known as GMAC (General Motors Acceptance Corporation), transformed into a leading digital-only financial institution in the United States. While many consumers recognize Ally primarily for its high-yield savings accounts and certificates of deposit (CDs), the institution maintains a prominent presence in consumer lending and credit products. Understanding how Ally credit works requires evaluating its distinct financial arms: credit cards, auto financing, specialized point-of-sale lending, and home mortgages.
Navigating consumer credit requires understanding both product eligibility and the mechanics of credit scoring. Whether an individual seeks to fund a vehicle purchase, earn cash-back rewards on daily purchases, or monitor their existing credit score, Ally provides specific credit vehicles tailored to varying credit profiles.
Disclaimer: This guide is intended for informational and educational purposes only and does not constitute formal financial, legal, or investment advice. Borrowers should review personal budgets and official disclosure documents from lenders before entering into binding credit agreements.
Ally Credit Cards: Features, Tiers, and Requirements
Ally offers a line of consumer credit cards designed to cater primarily to individuals with good-to-excellent credit profiles. Unlike many traditional brick-and-mortar issuers that accept open public applications across all product lines, Ally's credit card portfolio often operates on a combination of direct online applications and targeted pre-selected invitations.
Core Ally Credit Card Offerings
- Ally Cash Back Credit Cards: Designed for everyday spenders, these cards typically offer tiered cash-back rewards. Popular configurations include 3% cash back on high-frequency categories such as grocery stores, gas stations, and drugstores, alongside a baseline 1% cash back on all other eligible purchases.
- Ally Unlimited Cash Back Mastercard: This card provides a flat-rate cash-back structure (typically 2% on all qualifying net purchases) without category restrictions or rotating schedules, making it a streamlined option for general expense management.
- Ally Everyday Cash Back Mastercard: Aimed at households managing routine budgets, this product emphasizes higher return rates on common household category expenditures.
Eligibility Criteria and Application Mechanics
To qualify for an Ally credit card, applicants generally need a solid credit foundation:
- Credit Score Expectation: Applicants usually require a FICO Score in the Good to Exceptional range (typically 670 to 850). While applicants with scores in the mid-600s may occasionally be considered, lower risk profiles secure the lowest Annual Percentage Rates (APRs).
- Income and Debt Verification: Applicants must demonstrate a consistent source of income and maintain an acceptable Debt-to-Income (DTI) ratio, ideally below 36% to 40%.
- Pre-Approval vs. Direct Application: Ally periodically sends targeted pre-approval invitations containing unique reservation codes. Consumers can also visit Ally's official platform to check for pre-qualification offers using a soft credit inquiry, which does not impact their credit score.
Credit card account details, including billing statements and rewards redemptions, are managed through Ally's unified mobile app and web portal. Cash-back rewards can usually be redeemed directly as a statement credit or deposited into an eligible Ally Interest Checking or Online Savings Account.
Ally Auto Credit and Vehicle Financing
Auto financing remains one of Ally’s foundational pillars. As one of the largest automotive lenders in the United States, Ally Auto services millions of contracts for both new and used vehicles, as well as vehicle leases through direct dealership partnerships and direct customer refinancing programs.
How Ally Auto Credit Approvals Function
Ally Auto credit approvals differ significantly from consumer credit cards because auto loans are secured debt, backed by the vehicle itself as collateral. This collateralization allows Ally to consider a broader spectrum of credit scores compared to unsecured credit products.
- Prime Borrowers (FICO 660+): Prime applicants qualify for the lowest interest rates, reduced down payment requirements, and flexible repayment terms ranging from 24 to 84 months.
- Non-Prime and Subprime Borrowers (FICO below 660): Ally works with authorized dealership finance departments to structure non-prime auto loans. While interest rates are higher to offset risk, vehicle financing remains accessible to individuals rebuilding their credit history.
Loan vs. Lease Credit Evaluations
When evaluating a credit application for an auto lease versus an auto loan, Ally Auto applies distinct criteria:
[Auto Loan Application] ---> Evaluates: Debt-to-Income, Vehicle Value, Down Payment Result: Fixed Interest Rate & Loan Amortization [Auto Lease Application] ---> Evaluates: High Credit Tier, Residual Value, Mileage Limits Result: Lower Monthly Payment & Fixed Residual Value
Lease agreements generally demand stronger credit scores (typically 680 or higher) because the financial risk hinges on the vehicle's projected residual value at the end of the term. Consumers looking to finance a loan, however, can leverage larger cash down payments or trade-in equity to offset lower credit scores.
For borrowers seeking guidance on consumer lending protections, federal disclosures, and rights regarding vehicle financing, the Consumer Financial Protection Bureau (CFPB) provides comprehensive educational resources on auto loans.
Ally Lending and Home Financing Options
Beyond credit cards and auto loans, Ally operates specialized financing divisions aimed at direct consumer purchases and major life expenses: Ally Lending and Ally Home.
Ally Lending (Point-of-Sale Installment Loans)
Ally Lending provides point-of-sale (POS) installment loans directly through participating merchants, healthcare providers, and home improvement contractors. Instead of charging purchases to a revolving credit card, consumers can apply at the point of sale for fixed-rate installment credit.
- Fixed Repayment Schedules: Borrowers receive fixed monthly payments over established terms (e.g., 12, 36, or 60 months), eliminating the uncertainty of variable credit card interest rates.
- Soft Inquiry Pre-Qualification: Merchants integrated with Ally Lending can run initial eligibility checks using a soft credit pull, allowing consumers to view potential monthly payments and interest rates before completing a formal application.
Ally Home Loans
Ally Home provides mortgage solutions for home purchases and refinancing. Key credit parameters for Ally Home products include:
- Conventional Loan Minimum Score: Applicants generally require a minimum FICO Score of 620 for conventional mortgage financing.
- Jumbo Loan Requirements: For higher-value properties exceeding federal conforming loan limits, Ally requires credit scores of 700 to 740 or higher, alongside liquid cash reserve requirements.
- Zero Lender Fees: A unique feature of direct Ally Home loans is the elimination of application, processing, and underwriting fees, though standard third-party closing costs (escrow, title, appraisal) still apply.
Managing and Monitoring Your Credit Score with Ally
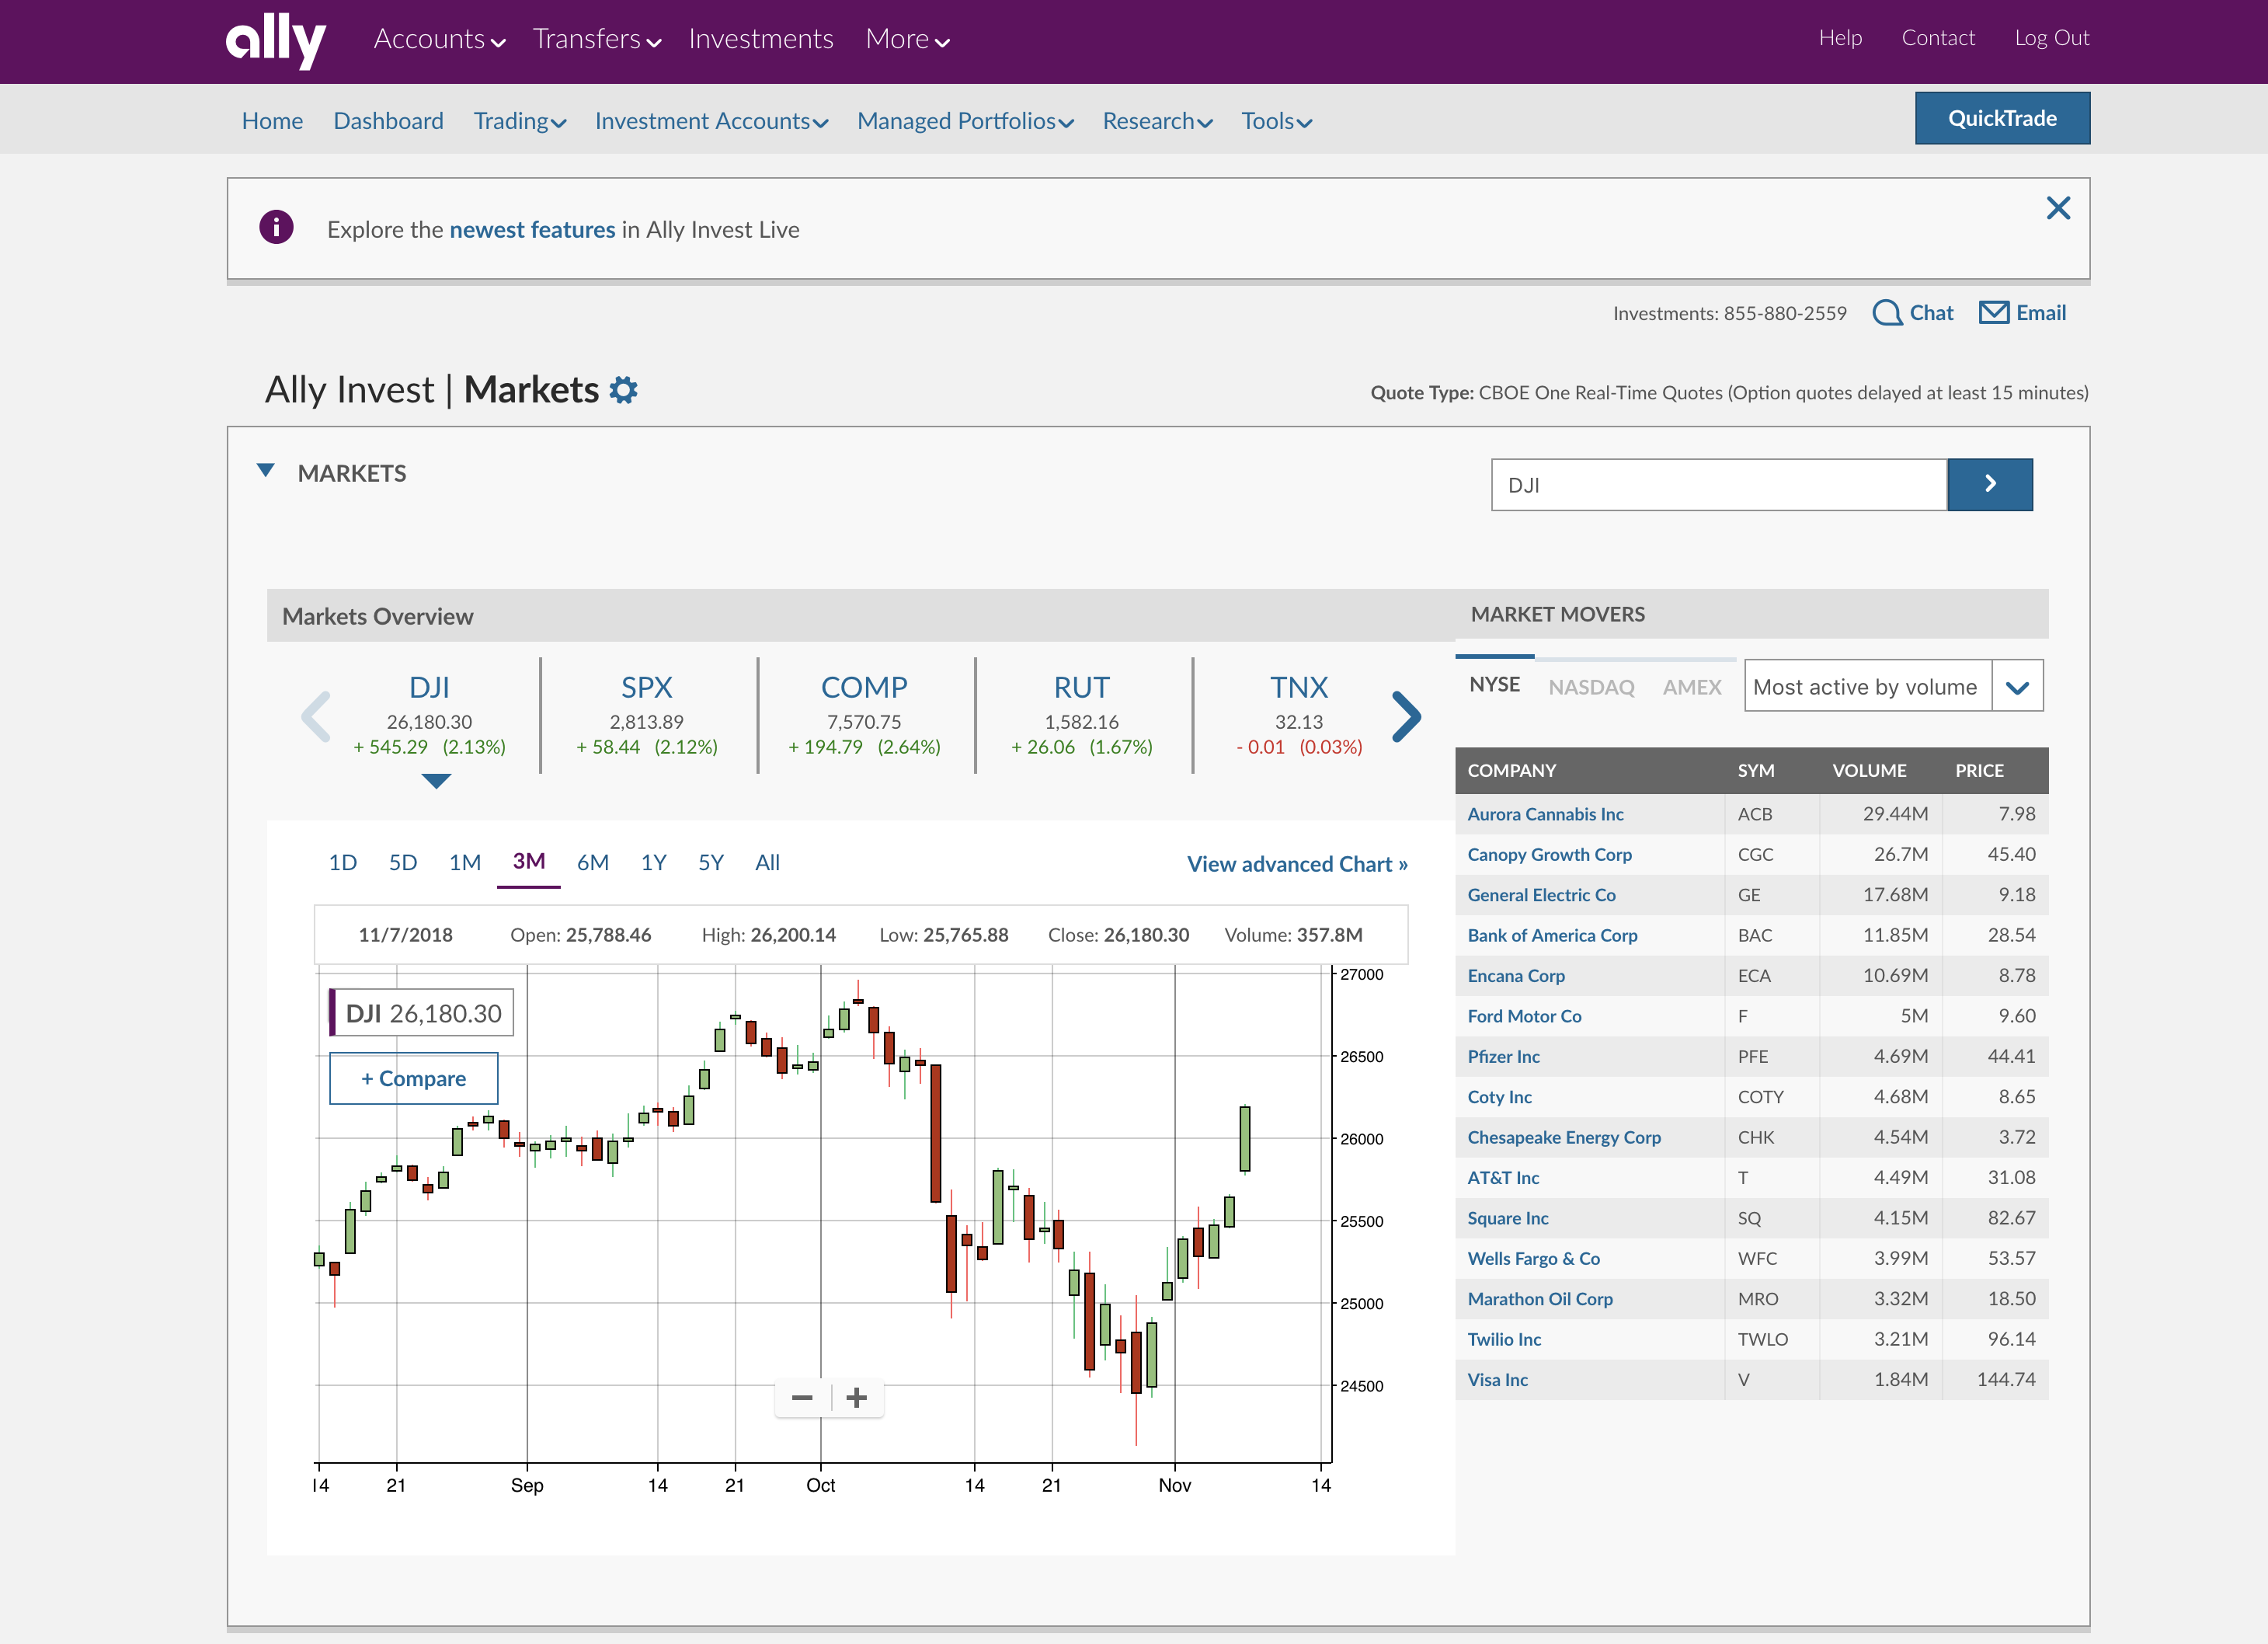
For existing banking customers, Ally offers integrated credit monitoring tools directly inside its online banking interface and mobile application. Understanding how this tool functions helps account holders track their financial health without incurring costs or damaging their credit files.
Free FICO Score Access
Ally partners with major credit reporting agencies to provide eligible credit card and deposit account customers with updated credit score tracking:
- Score Model: Ally primarily displays the FICO Score 8 model based on data from Experian. FICO Score 8 is the industry-standard scoring model used by the vast majority of consumer lenders.
- Update Frequency: Credit scores are refreshed automatically on a monthly basis, allowing users to track long-term score progression, swings in credit utilization, and account age milestones.
- Soft Pull Protection: Accessing your credit score through the Ally online portal is classified as an account-review soft inquiry. It is completely private and has zero impact on your credit score.
Key Factors Analyzed in Ally's Credit Dashboard
Inside the Ally credit dashboard, users can view breakdowns of the primary factors influencing their FICO Score:
- Payment History (35%): Tracks on-time payment performance across all reported accounts.
- Amounts Owed / Credit Utilization (30%): Measures total revolving balances relative to maximum credit limits. Maintaining utilization below 30% (and ideally below 10%) is recommended for optimal scoring.
- Length of Credit History (15%): Evaluates the average age of open accounts and the age of the oldest account.
- New Credit (10%): Monitors recent credit applications, hard inquiries, and newly opened lines of credit.
- Credit Mix (10%): Assesses the diversity of active accounts, such as revolving cards, auto loans, and mortgages.
Credit Bureau Reporting and Bureau Mechanics
When an individual holds an Ally credit product—whether a credit card, auto loan, or mortgage—Ally Financial reports account activity to all three major national credit bureaus: Equifax, Experian, and TransUnion.
Hard Inquiries vs. Soft Inquiries
Understanding how Ally accesses credit reports depends on the nature of the transaction:
- Soft Inquiries: Occur during pre-qualification checks, promotional credit card invitations, and monthly credit score updates within the Ally portal. Soft inquiries are visible only to the consumer and do not alter credit scores.
- Hard Inquiries: Occur when an individual submits a formal application for an Ally credit card, auto loan, personal installment loan, or mortgage. A hard inquiry allows Ally to view full credit details from one or more bureaus, resulting in a temporary drop of 2 to 5 points on the applicant's score.
To monitor your credit history across all three bureaus and check for unauthorized hard inquiries, consumers are entitled to free annual credit reports under federal law through AnnualCreditReport.com.
Account Reporting and FCRA Compliance
Under the Fair Credit Reporting Act (FCRA), enforced by the Federal Trade Commission (FTC), Ally is required to report accurate account details to credit repositories.
- Monthly Statement Reporting: Ally reports total account balances, current payment status, and monthly payment amounts shortly after each statement closing date.
- Late Payment Reporting: If an account holder misses a payment deadline, Ally typically offers a grace period before assessing late fees. However, if a payment becomes 30 days or more past due, Ally reports the delinquency to Equifax, Experian, and TransUnion, which can cause a substantial credit score decrease.
- Dispute Rights: If a consumer identifies an error on their credit report related to an Ally account—such as an incorrect balance or an inaccurate late payment mark—they have the legal right to file a dispute directly with the credit bureaus or through Ally’s official credit dispute processing department.
Comparing Ally Credit Products
To help prospective applicants compare their options, the following table synthesizes the core features, credit score guidelines, and bureau reporting standards across Ally’s credit portfolio:
| Product Name | Category | Target / Minimum FICO Score | Key Terms & Features | Bureau Reporting |
|---|---|---|---|---|
| Ally Cash Back Credit Cards | Unsecured Credit Card | 670+ (Good to Excellent) | Tiered cash back (e.g., 3% groceries/gas, 1% other); $0 annual fee options | Equifax, Experian, TransUnion |
| Ally Auto Financing | Auto Loan / Lease | 600+ (Varies by dealer/tier) | Competitive fixed APRs; terms from 24 to 84 months; dealer network access | Equifax, Experian, TransUnion |
| Ally Lending | Point-of-Sale Installment | 640+ (Varies by merchant) | Fixed monthly terms; POS financing for healthcare & home improvement | Equifax, Experian, TransUnion |
| Ally Home Loans | Residential Mortgage | 620+ (Conventional) | $0 lender fees; fixed and adjustable-rate options; digital portal | Equifax, Experian, TransUnion |
Practical Strategies to Qualify for Ally Credit
Applying for credit requires strategic preparation to maximize approval odds and secure competitive interest rates. Prospective applicants should consider the following steps before applying for an Ally credit product:
1. Optimize Your Credit Utilization Ratio
For revolving lines of credit, such as credit cards, lower credit utilization signals financial stability to underwriters.
- Calculate your utilization ratio using the formula: $$\text{Credit Utilization} = \left( \frac{\text{Total Revolving Balances}}{\text{Total Credit Limits}} \right) \times 100$$
- Pay down existing credit card balances prior to submitting a new application to keep your overall utilization below 30%, with optimal results under 10%.
2. Audit Your Credit Reports for Errors
Before submitting an application that triggers a hard credit inquiry, obtain copies of your credit reports from Equifax, Experian, and TransUnion. Verify that personal identification details, account balances, and payment histories are correct. Correcting erroneous late payments or inaccurate collection accounts before applying can significantly boost your scoring tier.
3. Lower Your Debt-to-Income (DTI) Ratio
Underwriters for Ally Auto, Ally Home, and Ally Lending evaluate your monthly debt commitments relative to gross monthly income: $$\text{DTI Ratio} = \left( \frac{\text{Total Monthly Debt Payments}}{\text{Gross Monthly Income}} \right) \times 100$$ A DTI ratio under 36% presents a low risk profile, while a DTI above 43% may result in conditional approvals, higher interest rates, or outright application denials.
4. Leverage Existing Relationships with Ally Bank
Holding an active Interest Checking, Online Savings, or Money Market Account with Ally Bank can streamline the application process. While an existing deposit relationship does not guarantee credit approval, it provides Ally with verification of cash flow and account history, which can support overall underwriting evaluations.
Frequently Asked Questions
What credit score do I need to get approved for an Ally credit card?
Most Ally credit card offerings require a Good to Exceptional credit score, typically defined as 670 or higher on the FICO scoring scale. Applicants with scores above 740 generally secure the lowest Annual Percentage Rates (APRs) and higher initial credit limits.
Does checking my credit score through Ally Bank harm my score?
No. The credit score feature in the Ally Online Banking portal uses a soft inquiry, which does not impact your credit score. You can check your score as frequently as you like without affecting your credit rating.
Which credit bureau does Ally Bank pull for applications?
Ally Financial may pull credit reports from any of the three major national credit reporting agencies: Experian, Equifax, or TransUnion. The specific bureau selected depends on the borrower's state of residence and the specific product type (auto loan, credit card, or mortgage).
How long does it take Ally to report payments to credit bureaus?
Ally typically reports account data and payment updates to Equifax, Experian, and TransUnion once per month, shortly after your monthly statement billing cycle closes. It can take between 3 to 10 business days after your statement date for the updated information to appear on your official credit reports.
Can I apply for an Ally credit card without an invitation?
While many Ally credit card offers historically circulated via mail invitations containing pre-approval reservation codes, Ally periodically allows direct online pre-qualifications through its web portal. Visiting Ally’s official website allows you to check for current direct application availability using a soft credit pull.
Final Guidance and Next Actions
Understanding the mechanics of Ally credit enables borrowers to choose the right financial product while protecting their long-term financial health. Whether seeking a revolving credit card for everyday rewards, financing a vehicle through Ally Auto, or leveraging point-of-sale loans via Ally Lending, preparation is key.
Next Action Steps:
- Log into your existing banking portal or visit AnnualCreditReport.com to review your current credit score and report details.
- Pay down outstanding revolving debt balances to bring overall credit utilization below 30%.
- Utilize soft-pull pre-qualification tools on Ally's official website where available to test your eligibility before committing to a hard credit inquiry.